top of page


Energy Consultancy | Wellhead to Global LNG, Sustainability and AI


NG/LNG - This Week's Main Drivers and the Look Ahead | 9.27.26
Source: EIA This Week's Main Drivers: EIA storage increased +53 BCF, versus +77 BCF last year and +76 BCF for the five-year average. YTD injections remain materially below last year, reinforcing the tighter seasonal setup. October gas broke above $3/MMBtu as Columbia Gas declared Force Majeure on TCO Line 100, impacting roughly 1.8 BCF/D and triggering significant short covering. The U.S. nuclear fleet is entering fall maintenance/refueling, while Cove Point LNG began its ann

Timothy Beggans
7 days ago2 min read


The Gas Market Is Split in Two. Winter Will Decide Which Side Breaks.
Source: To Europe & Beyond The global natural gas market is increasingly divided into two worlds. The U.S. has relatively abundant gas and expanding LNG capacity, while Europe and Asia remain exposed to constrained global LNG supply, geopolitical risk and winter weather. That disconnect is the story — and the risk. Why the Market Has Split U.S. gas remains structurally cheaper because production is strong and LNG export capacity, while expanding, cannot instantly absorb every
Timothy Beggans
Sep 262 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 9.20.26
Source: EIA This Week's Main Drivers: EIA storage increased +44 BCF well below last year's +87 BCF and the five-year average of +74 BCF—another materially bullish storage signal. Yet natural gas remains unable to break and hold above $3/MMBtu. LNG operations remain a key variable. Cameron LNG lost one train mid-week, while Golden Pass Train 1 continues its slow ramp, now around 62%. Meanwhile, the Strait of Hormuz remains severely restricted, with LNG flows still disrupted. A
Timothy Beggans
Sep 202 min read


The Gamblers: When Net Zero Collides With Energy Security
Source: UK Department for Energy Security & Net Zero Britain is approaching winter with a dangerous energy-security equation: very low gas storage, heavy dependence on imports, and a weather wildcard that cannot be forecast with certainty. The UK’s only large-scale gas storage facility, Rough, is practically empty. Centrica says the market currently does not make storage commercially viable without a supporting framework. Rough can hold up to 54 Bcf—roughly enough to heat 2.4
Timothy Beggans
Sep 192 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 9.13.26
Source: EIA This Week's Main Drivers: EIA NG Storage: +40 BCF vs. +69 BCF last year and the +52 BCF 5-year average. The smaller injection keeps the storage deficit narrative alive as we approach winter. Crude oil rocketed above $100/BBL. as the Iran-US war continues to disrupt energy flows and effectively shut the Strait of Hormuz to LNG exports. No LNG tankers transited Hormuz Wednesday, underscoring the severity of the disruption. Summer heat is finally retreating, with the
Timothy Beggans
Sep 132 min read


Qatar Is Boxed In. Could Saudi Arabia Throw It a $30 Billion Lifeline?
Source: 2b1st The Strait of Hormuz crisis is forcing Gulf producers to rethink a fundamental question: Can natural gas reach global markets without passing through Hormuz? One intriguing possibility is Saudi Arabia. Saudi Arabia already has the Master Gas System (MGS) connecting major gas-producing and processing assets across the Kingdom. Aramco is expanding the system toward 17.5 Bcf/d by 2028. But here's the bigger idea: Could Saudi Arabia eventually extend its gas infrast
Timothy Beggans
Sep 122 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 9.6.26
Source: EIA This Week’s Main Drivers: The EIA reported a +30 BCF storage injection—right on expectations, but bullish versus +50 BCF last year and the +37 BCF five-year average. The storage surplus to the five-year average continues to narrow. Tropical Storm Edouard delivered heavy rain across East Texas, but had little apparent impact on LNG exports. Meanwhile, low Texas wind generation and weaker solar output increased gas-fired power demand, while the South Central salt-st
Timothy Beggans
Sep 62 min read


India vs. China LNG in 2026: Two Asian Giants, Two Very Different Demand Signals
Source: Marine Traffic China remains the larger LNG importer, with 2026 imports projected at roughly 61–64 million MT, versus 28–29 million MT for India. But the more important story this year is how differently the two markets responded to the Iran-US conflict and the disruption of Middle Eastern LNG flows. Month-by-Month Jan–Feb: Demand was relatively normal before the conflict. India imported about 4.45 MT combined, while China’s February imports fell to approximately 3.38
Timothy Beggans
Sep 52 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 8.30.26
This Week's Main Drivers: Storage: EIA reported a +15 Bcf injection, versus +17 Bcf last year and the +33 Bcf 5-year average—another bullish signal for near-term gas demand. Texas heat: Excessive heat remains locked into Texas into September. Low wind generation is adding to ERCOT gas burn, while South Central salt storage drew 20 Bcf this week, potentially setting up another large draw next week. Global LNG: Qatar is cutting government spending by as much as 30% as the Iran
Timothy Beggans
Aug 302 min read


China Is Walking Away From Spot LNG — Is This a Structural Shift?
Source: CGTN Frontline (China) China’s LNG appetite is changing—and the implications for global gas markets could be significant. China’s 2026 LNG imports are tracking toward 61–64 million tonnes, down from 68.4 million tonnes in 2025. That would mark a second consecutive annual decline. The IEA estimates Chinese gas demand fell 4% YoY from March–June, while LNG imports dropped roughly 12%. This looks increasingly structural. High LNG prices and the Iran/Hormuz disruption exp
Timothy Beggans
Aug 292 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 8.23.26
The Week’s Main Drivers: The U.S. natural gas market continues to balance record supply against weather-driven demand and rising LNG exports. • EIA Storage: +16 Bcf injection vs. +19 Bcf last year and the 5-year average of +29 Bcf — a notably bullish storage print. • LNG flows: Spot cargoes are increasingly tracking toward Europe as regional supply risks persist. Norway’s Ormen Lange outage has been extended to February 1, 2027, removing an important source of European supply
Timothy Beggans
Aug 232 min read


Europe Is Skating on Thin Ice: The Gas Storage Gamble Gets Riskier
Source: Gassco Europe’s natural gas market is entering winter with little room for error. Storage remains below last year’s levels, LNG competition is intensifying, and another Norwegian supply disruption is making the margin even thinner. Ormen Lange: Another Hole in the Boat Norway’s Ormen Lange field has become an increasingly important concern. One of its two subsea compressor stations is out of service following a technical failure, cutting production by approximately 8.
Timothy Beggans
Aug 222 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 8.16.26
Source: EIA This Week’s Main Drivers: The U.S. natural gas market continues to balance strong summer demand against growing winter uncertainty. EIA storage increased 36 Bcf, slightly above the 32 Bcf expectation, compared with 49 Bcf last year and the 33 Bcf five-year average. The injection keeps storage fundamentals relatively comfortable, but the weather outlook is becoming more complicated. Strait of Hormuz traffic has fallen to a three-month low, keeping global energy sec
Timothy Beggans
Aug 162 min read


Will Summer Doldrums Lead to Winter Volatility?
Source: WXCharts.com Natural gas markets have become increasingly comfortable with lower prices. Storage injections remain healthy, summer demand is beginning to ease, and many traders have embraced the bearish narrative. But when everyone is on the same side of the trade, it often pays to ask: what could change? Several developing trends suggest today's complacency could give way to a much different winter. Meteorologists continue to monitor the evolution of a potential Supe
Timothy Beggans
Aug 82 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 8.2.26
Global natural gas markets remain increasingly driven by geopolitics, weather, and LNG infrastructure reliability. While U.S. storage remains healthy, tightening global supply risks continue to support longer-term volatility. This Week's Main Drivers • EIA Storage: +28 Bcf, below the +36 Bcf consensus, signaling balanced supply despite strong summer demand. • August NYMEX Expiration: The August natural gas contract settled at $2.725/MMBtu, keeping pressure on producers while
Timothy Beggans
Aug 22 min read
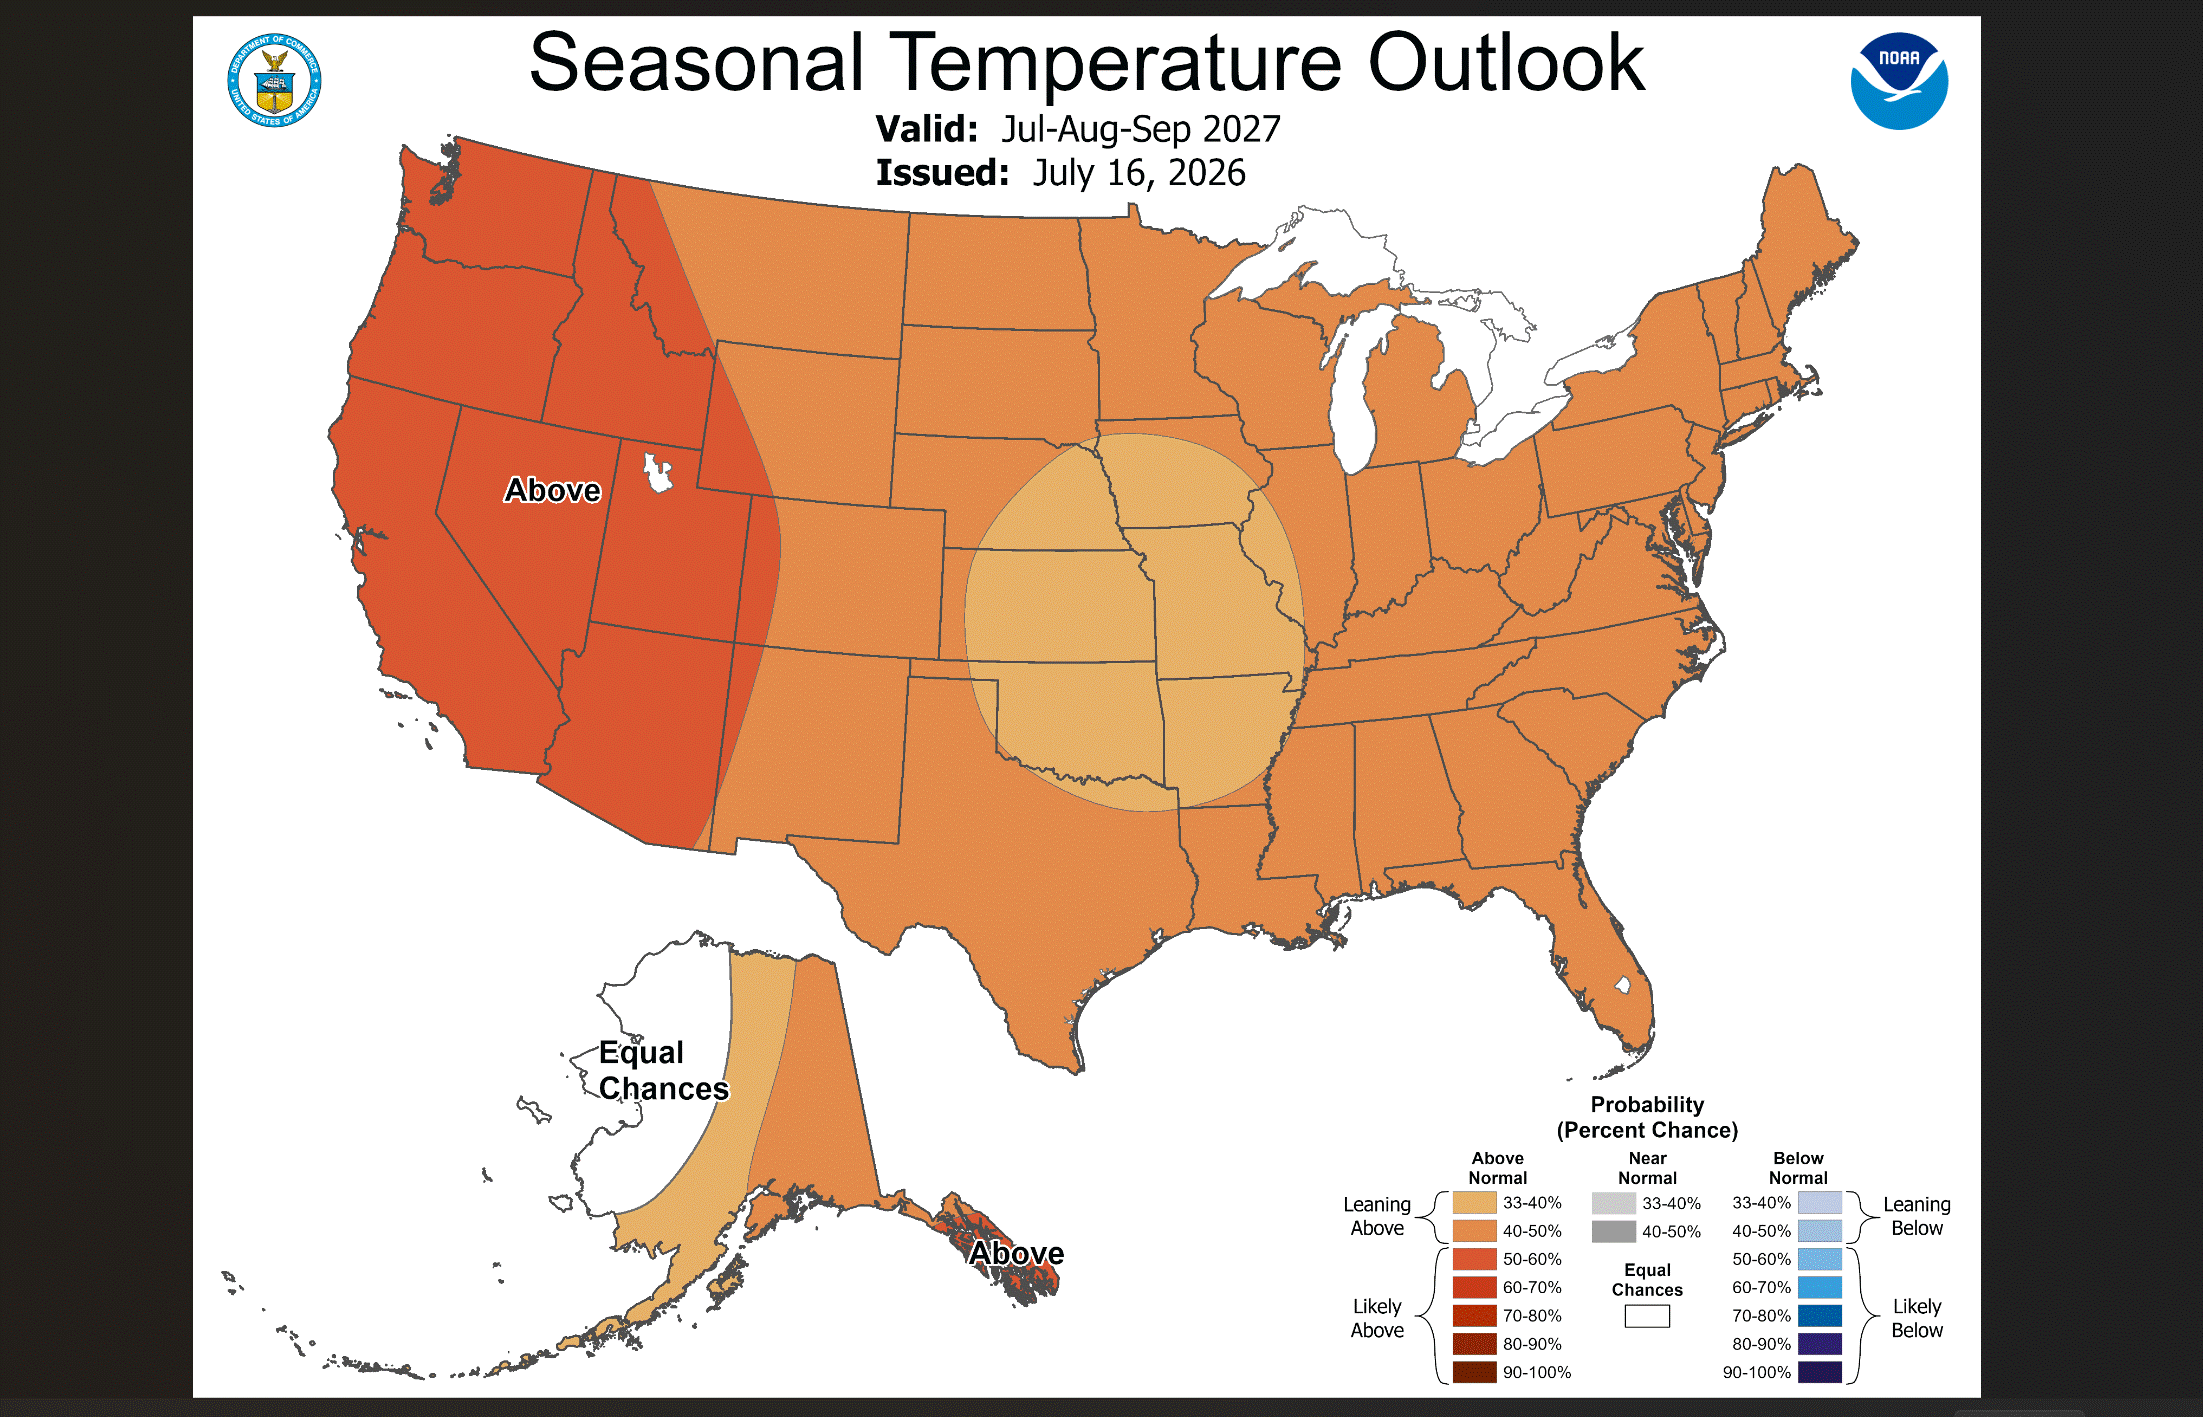
Could a Super El Niño Rewrite the Natural Gas Outlook for the Next 12 Months?
Source: NOAA Most natural gas traders are focused on storage, LNG exports, and geopolitics. But one of the biggest market drivers over the next year may already be forming in the Pacific. NOAA's latest outlook indicates a 97% probability that El Niño persists through early spring 2027, with an 81% chance of strengthening into a very strong event. If history is any guide, a Super El Niño could reshape weather patterns well beyond this winter. For natural gas markets, the first
Timothy Beggans
Aug 12 min read


NG/LNG – This Week's Main Drivers and the Look Ahead | 7.26.26
Source: EIA This Week's Main Drivers: The EIA reported a +32 Bcf storage injection, slightly tighter than expectations (+35 Bcf) and above both last year (+27 Bcf) and the five-year average (+30 Bcf). The report was largely neutral but reinforced a tightening supply-demand balance. Geopolitics dominated headlines as Qatar extended Force Majeure on LNG exports into mid-October, an LNG vessel was struck by a projectile in the Strait of Hormuz, and the Iran conflict intensified.
Timothy Beggans
Jul 262 min read


Europe's Winter Gas Reckoning: Can Low Storage Withstand a New Geopolitical Shock?
Source: Al Jazeera (Yemen) Europe is heading into the 2026-27 heating season with one of its weakest natural gas cushions in years. Storage remains well below last year's level and the five-year average, increasing the likelihood of heightened price volatility if winter demand exceeds expectations. The market's greatest uncertainty isn't just storage—it's geopolitics. Iran continues to use the threat of disrupting the Strait of Hormuz as leverage in negotiations over its nucl
Timothy Beggans
Jul 252 min read


NG/LNG - This Week's Main Drivers and the Look Ahead | 7.19.26
Source: EIA This Week's Main Drivers: Natural gas markets continued to wrestle with conflicting signals. The EIA reported a +41 Bcf storage injection versus expectations of +37 Bcf, reinforcing that supply remains adequate despite elevated summer demand. The Strait of Hormuz once again became a focal point for global energy markets, reminding traders how quickly geopolitical risk can influence LNG pricing and global gas flows. Domestically, Freeport LNG remains largely offlin
Timothy Beggans
Jul 192 min read


Is Europe Betting on a Mild Winter While U.S. LNG Prepares for the Worst?
Source: NOAA As the calendar moves toward winter, the global natural gas market is quietly shifting from summer injections to winter risk management. Europe enters the second half of the refill season with natural gas storage only 52% full, compared with 60% at the same point last year. Several key countries—including Great Britain, Belgium, and the Netherlands—are sitting at or near five-year storage lows, leaving less margin for error if cold weather arrives early. At the s
Timothy Beggans
Jul 182 min read
bottom of page